A board gets a $9,400 bid to patch and seal the community's private road. Somebody asks whether that comes out of reserves. Half the room says yes because it is the road. The other half says no because it is not a replacement.
Both halves are arguing about the same thing without naming it: is this maintenance, or is it capital work? The answer decides which fund pays, how the treasurer records it, and occasionally whether owners get a say.
The three categories
Maintenance keeps a component going through its expected life. Sealcoating asphalt, cleaning gutters, servicing the pool pump, repainting trim on the normal cycle. These are recurring, roughly predictable, and belong in the operating budget.
Replacement swaps a component out at the end of its life for something equivalent. New shingles on the same roof, a new pool pump of the same type, repaving the same road on the same footprint. These are the items in your reserve study, and reserves are what they are for.
Capital improvement adds something the community did not have, or upgrades a component beyond equivalent replacement. A new dog park. Converting a gravel path to concrete. Replacing a functional wood fence with wrought iron because owners prefer it. Adding cameras at the entrance.
The line between the second and third categories is where boards get into trouble, because a capital improvement usually is not funded in the reserve study and may carry different approval requirements.
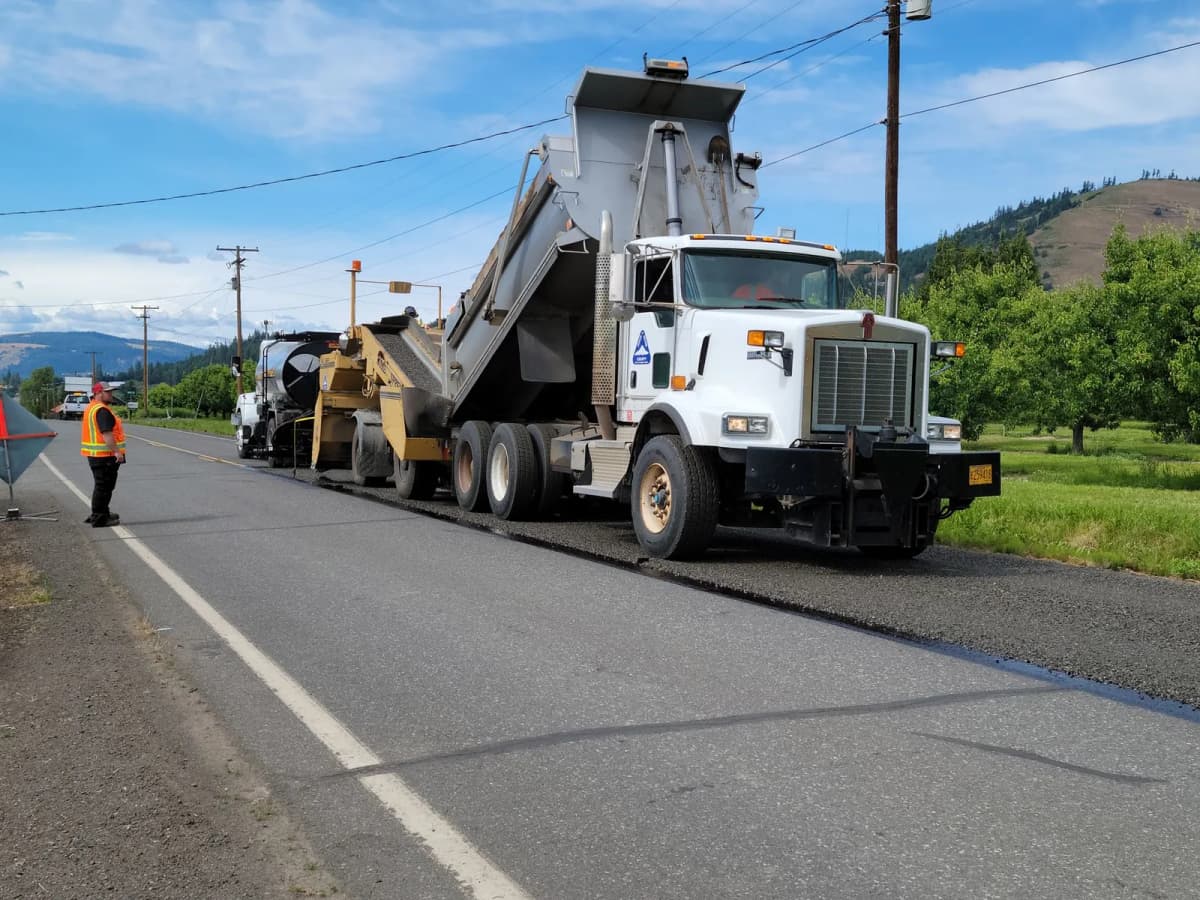
Photo by Tom Shamberger on Pexels
A test that holds up
Ask three questions in order.
Is the component already in the reserve study? If yes, and the work is bringing it back to its original condition or function, you are in maintenance or replacement territory. If the component is not in the study at all, find out why before you classify anything. A missing component usually means a stale study, not an improvement.
Does the work restore the component, or change it? Patching a roof gets you through the season. Replacing the roof restores it and restarts the clock. Adding a second layer of insulation while you are up there changes the asset. The first is maintenance, the second is replacement, the third has an improvement component in it.
Would a reasonable owner call this "new"? Not a legal test, but a useful one. If an owner walking the property would notice something that was not there before, the board should treat it as an improvement and handle the approval accordingly.
Accounting draws the same line. A capital expenditure is spending that obtains or upgrades a physical asset expected to be useful for more than a year, and it gets recorded as an asset rather than charged straight to expense. Routine upkeep is charged in the period it happens. Federal tax rules follow the same logic for tangible property: the IRS final tangible property regulations require capitalizing amounts paid to improve property, while amounts that are not improvements are generally deductible as repairs and maintenance. That is a recording question rather than a funding one, and your association's own filing position belongs with your CPA, but the line falls in the same place your budget needs it to.
Worked examples
Roof. Replacing 40 damaged shingles after a hailstorm is maintenance, paid from operating. A repair that small will usually fall below the wind and hail deductible, so do not assume insurance picks it up. Tearing off and replacing the whole roof at the end of its rated life is replacement, paid from reserves. Replacing an asphalt-shingle roof with metal because the board wants a 50-year product is replacement plus an improvement component, and the upgrade portion needs its own funding decision.
Private road. Crack sealing and pothole patching: maintenance. Mill and overlay at end of life: replacement. Widening the road or adding a turn lane: improvement.
Pool. Chemicals, weekly service, replacing the filter cartridge: maintenance. Resurfacing the shell on its 12-year cycle: replacement. Adding a splash pad: improvement.
Fencing. Repairing storm-damaged panels: maintenance. Replacing the whole perimeter fence in the same material: replacement. Upgrading to a different, more expensive material: replacement for the equivalent cost, improvement for the difference.
A single project can split across two funds. The honest way to handle it is to price the equivalent replacement, charge that to reserves, and treat the delta as an improvement with its own approval path.
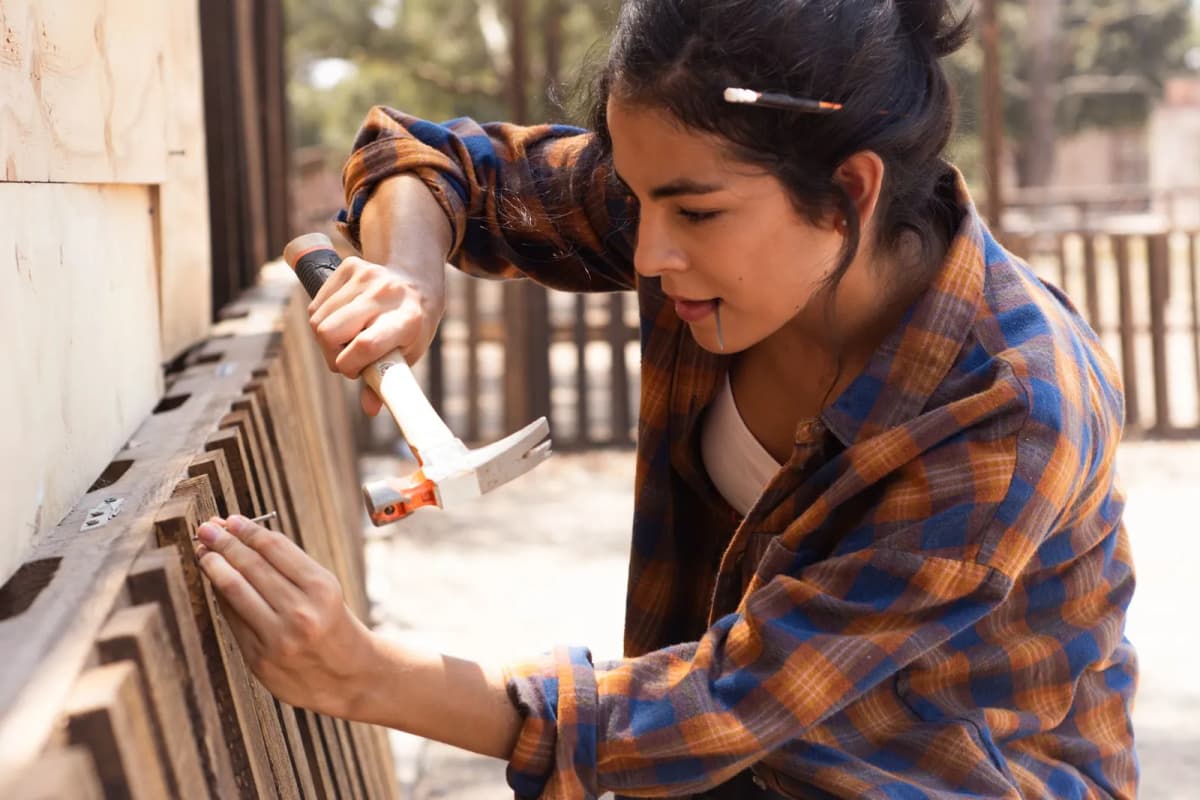
Photo by Los Muertos Crew on Pexels
Approval is where documents matter
Many declarations limit what a board can spend on a capital improvement without an owner vote, often with a dollar threshold or a percentage of the annual budget. Some state statutes add their own limits. Replacement of an existing component usually sits inside the board's ordinary authority, which is exactly why the classification is not a semantic argument.
Read your declaration and bylaws before committing to an improvement, and if the threshold language is ambiguous, get an opinion rather than a consensus. A board that spends reserve money on an improvement it was not authorized to approve is exposed to a challenge from any owner who objects, and good intent is not a defense to it.
Why the distinction protects the reserve fund
Every dollar of reserve money spent on something that was not in the study moves a replacement date closer without moving the funding. Do it twice and the reserve fund that looked healthy in January is behind by December. This is one of the quieter ways communities end up underfunded, and it never shows up as a single bad decision.
Classify the expense before you approve it, record it in the fund that owns it, and note the reasoning in the minutes. Future boards will be able to reconstruct what happened, which is most of what good records are for.
Related Reading
- How to Create an HOA Budget (And What Boards Get Wrong)
- HOA Reserve Studies: What They Are and Why You Need One
- HOA Reserve Fund: How Much Is Enough for Your Board?
A classification only holds if it is still traceable afterward. HOA-OS keeps the component list, the reserve schedule, and the spending record together, so three boards from now it is still obvious which fund a decision came out of and why. Get in touch.